
Trying to pin down the “average cost of car insurance” can feel a little like trying to guess the price of a house without knowing the city, the neighborhood, or even how many bedrooms it has. It’s a helpful starting point, but the details are what really matter.
Nationally, the average driver pays around $2,638 per year for a full coverage policy. But if you live in Florida, that number tells a very different story. Here, the average skyrockets to $4,171 annually, a figure that paints a clear picture of just how much your zip code can influence your rates.
Annual Car Insurance Cost National vs Florida
Let’s put those numbers side-by-side to see the difference. Here’s a breakdown of what you can expect to pay for a full coverage policy on average, both across the country and right here in Florida.
- National Average:
- Annual Premium: $2,638
- Monthly Premium: ~$220
- Florida Average:
- Annual Premium: $4,171
- Monthly Premium: ~$348
The gap is significant, isn’t it? That nearly $1,500 difference isn’t an accident. It’s a direct result of Florida’s unique driving environment, from our wild weather to the sheer volume of cars on our roads. If you’d like to dig deeper, you can discover more insights about these rising auto insurance costs and what’s behind them.
Full Coverage Versus Minimum Requirements
So, what are you actually paying for? When insurers talk about “full coverage,” they’re not referring to a single, off-the-shelf product. It’s really just shorthand for a policy that bundles together several essential types of protection.
Think of it as a comprehensive safety net. A typical full coverage policy includes:
- Liability Coverage: This is the bare minimum required by law. It pays for the damage you cause to other people and their property. In Florida, this is broken down into Property Damage Liability (PDL) and Personal Injury Protection (PIP), which covers your own initial medical costs.
- Collision Coverage: This is what pays to fix your car if you hit another vehicle, a guardrail, or any other object. Without it, you’re on your own for repair bills after an at-fault accident.
- Comprehensive Coverage: This handles just about everything else. It covers damage from events that aren’t a collision, like theft, a tree falling on your car, vandalism, or a hurricane—an absolute must-have in Florida.
Now, let’s compare that to what Florida legally requires. The state minimum is just $10,000 in PIP and $10,000 in PDL. That’s it.
Opting for the state minimum is definitely the cheapest route, but it leaves you incredibly vulnerable.
A minimum policy won’t pay a dime for injuries you cause to others in an accident, and it won’t cover your own car’s repairs if you’re at fault. It’s a massive financial gamble that could leave you on the hook for tens or even hundreds of thousands of dollars.
Ultimately, choosing your coverage level is a balancing act between your budget and how much risk you’re comfortable with. Full coverage costs more upfront, but it can be the one thing that prevents a bad day on the road from becoming a life-altering financial disaster.
The Hidden Factors That Determine Your Premium
Ever wonder why your car insurance quote feels so personal—and often, so high? It’s not just a random number. Think of it as a personalized risk score, where insurers act like oddsmakers calculating the odds you’ll file a claim.
Every detail about you, your car, and where you drive adds or subtracts from that score, directly shaping your final price. This process goes way beyond the national average, diving deep into the “why” behind what you pay. Let’s pull back the curtain on the most significant factors that influence your premium.
Your Personal Driving Profile
The starting point for any insurance rate is you. Insurers rely on statistical trends to predict future behavior, and several personal details are strongly tied to risk.
- Your Age and Experience: It’s a fact of life for younger drivers. Those under 25 statistically get into more accidents, simply because they have less time behind the wheel. This translates directly to higher premiums. As drivers mature, rates typically drop, though they can start to creep up again for seniors over 70.
- Your Driving Record: This is arguably the biggest piece of the puzzle. A clean record—no accidents, DUIs, or tickets—sends a clear signal to insurers that you are a low-risk driver. On the other hand, understanding the impact of a speeding ticket on your car insurance rates is crucial, as even a single violation can cause a significant spike.
- Your Credit History: In Florida, insurers can use a credit-based insurance score to help set your rates. The data shows a link between how someone manages their finances and how likely they are to file a claim. A solid credit history can often lead to lower insurance costs.
The Vehicle You Drive
Not all cars are created equal in the eyes of an insurer. The specific vehicle you want to cover plays a huge role in the math, as it’s directly tied to potential repair and replacement costs.
A brand-new luxury SUV will always cost more to insure than a 10-year-old sedan. Insurers look at the car’s market value, the typical cost of repairs for that specific make and model, and its safety ratings. Cars loaded with advanced safety features, like automatic emergency braking or anti-theft systems, might even earn you a discount.
Insurers also pay close attention to theft statistics. If you happen to drive a model that is a popular target for thieves, your comprehensive coverage premium will likely be higher to account for that increased risk.
Where You Live and Drive
Your location is a critical piece of the puzzle, especially here in Florida. Insurance companies analyze claim data right down to the zip code, and living in an area with more risk means paying more for your policy.
For instance, a driver in a dense urban hub like Tampa will almost always pay more than someone in a quiet, rural town. That’s because cities have higher rates of traffic congestion, accidents, vehicle theft, and vandalism. But in Florida, the risks don’t stop there.
The infographic below breaks down the core components of a full coverage policy, which is essential protection against the unique risks we face on Florida’s roads.
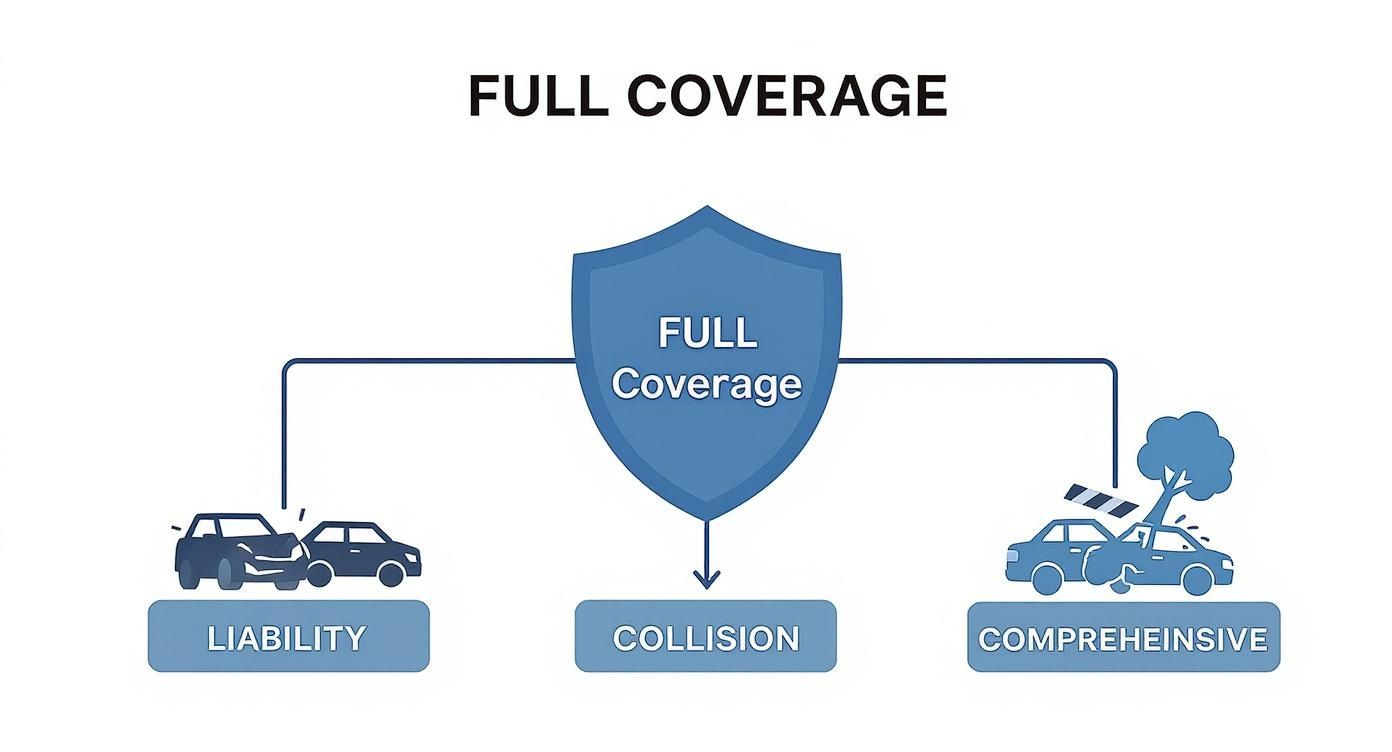
This visual really clarifies how liability, collision, and comprehensive coverages work together to form a protective shield for drivers.
Florida’s Unique Risk Factors
On top of the standard pricing factors, Florida drivers face a unique storm of challenges that dramatically inflate car insurance costs across the state. These local issues create a high-risk environment that insurers have no choice but to price into your policy.
- Severe Weather: Florida’s constant threat of hurricanes, tropical storms, and flooding means there’s a much higher chance of widespread vehicle damage. That elevated risk is baked directly into your comprehensive coverage rates.
- High Population Density: Our roads are crowded, especially in busy corridors like I-4 through Tampa and Orlando. More cars on the road inevitably lead to more accidents and, you guessed it, more claims.
- Insurance Fraud: Unfortunately, Florida has long been a hotspot for fraudulent claims, especially those related to Personal Injury Protection (PIP). This widespread problem forces insurers to raise rates for everyone to cover those fraudulent losses.
- Uninsured Drivers: The state has one of the highest rates of uninsured motorists in the entire country. This is a massive problem, as it leaves responsible, insured drivers holding the bag after an accident. To better understand this issue, check out our guide on navigating claims after an accident with an uninsured driver in Florida.
Each of these factors contributes to why your policy costs what it does, turning a simple quote into a complex reflection of your personal risk profile.
How Your Coverage Choices Build Your Final Price
Think of your car insurance policy less like a fixed product and more like building a custom meal. You start with the basics, but the final cost really comes down to the extra ingredients you choose to add. Every decision you make—from the bare minimum to a fully loaded plan—directly shapes your premium, turning that generic “average cost” into a number that’s all yours. Getting this balance right is the key to feeling protected without breaking the bank.
In Florida, every policy has to start with a specific foundation of legally required coverages. These are the absolute non-negotiables for driving on public roads, and they form the base layer of your insurance cost.
Florida’s Mandatory Insurance Foundation
To legally drive in the Sunshine State, you have to carry two specific types of coverage. Consider them your entry ticket to the road, but be warned—they offer very limited protection on their own.
- Personal Injury Protection (PIP): Florida is a “no-fault” state, which is just a technical way of saying your own insurance pays for your initial medical bills after a crash, no matter who caused it. The law requires you to carry at least $10,000 in PIP to cover your immediate medical care and lost wages.
- Property Damage Liability (PDL): This is for the other person’s stuff. If you cause an accident, PDL pays to fix their car, the mailbox you hit, or any other property you damage. The state minimum here is also $10,000.
A policy with just these two coverages will always be the cheapest option. But it leaves you dangerously exposed. Notice what’s missing? There is zero coverage for injuries you might cause to another person.
Building Beyond the Basics with Optional Coverages
This is where you shift from just being “legal” to being financially smart. Each of these optional coverages adds to your premium, but they also plug potentially devastating holes in your financial safety net.
Bodily Injury Liability (BIL): Honestly, this is one of the most important coverages you can buy. If you cause an accident that injures or kills someone, BIL is what pays for their hospital bills, lost income, and even their pain and suffering. Without it, you could be sued personally and face financial ruin.
Uninsured/Underinsured Motorist (UM/UIM): With a startling number of uninsured drivers on Florida’s roads, UM/UIM coverage is practically a necessity. It acts as your personal safety net, stepping in to pay your medical bills when you’re hit by a driver who has no insurance or not nearly enough to cover the damage they caused.
Choosing your coverage levels is a direct trade-off between today’s cost and tomorrow’s security. A bare-bones policy saves you a few bucks now, but one bad accident can unravel everything you’ve worked for. A stronger policy costs more, but the peace of mind is often priceless.
The national average annual cost for car insurance is around $2,320, which breaks down to about $193 per month. But that number is all over the place depending on the coverages people choose and which company they’re with. You can learn more about these car insurance cost findings to see just how much prices can vary from one carrier to the next.
Adding Protection for Your Own Vehicle
So far, we’ve talked about covering damage to other people or injuries from an uninsured driver. But what about your own car? That’s where Collision and Comprehensive come into play.
- Collision Coverage: This pays to fix or replace your car if it’s damaged in a crash with another vehicle or an object, like a guardrail or a telephone pole. It kicks in no matter who was at fault.
- Comprehensive Coverage: This handles almost everything else—all the non-collision stuff. It’s crucial in Florida, as it covers theft, vandalism, fire, flooding, and damage from falling tree limbs during a hurricane.
These coverages are especially important if you have a newer car or a loan on your vehicle.
For a deeper look at what these policies cover, you can learn more about comprehensive car insurance coverage in our article and see why it’s so critical for anyone living in Florida. By adding these protections and tweaking your deductibles, you can build a policy that truly fits your needs and budget.
Impact of Coverage Levels on Florida Annual Premiums
To see this in action, look at how dramatically premiums can change as you move from a basic policy to one with robust protection. Here is a breakdown of estimated annual premium ranges based on different coverage levels in Florida:
- State Minimum Policy:
- Key Coverages: Includes the legally required $10,000 in PIP and $10,000 in PDL.
- Estimated Annual Premium Range: $800 – $1,400
- Liability Only Policy:
- Key Coverages: Adds Bodily Injury Liability (e.g., 50/100/25 limits) to the state minimums.
- Estimated Annual Premium Range: $1,500 – $2,500
- Full Coverage Policy:
- Key Coverages: Adds Collision, Comprehensive, and Uninsured/Underinsured Motorist (UM/UIM) coverage.
- Estimated Annual Premium Range: $2,800 – $4,500+
This breakdown makes it clear: the jump from a “legal” policy to a “protective” one is significant, but it buys you security against worst-case scenarios. Ultimately, every additional coverage you select contributes to a final price that reflects the level of protection you’re comfortable with.
See How Real Florida Drivers Are Priced
Statewide averages and abstract numbers can only tell you so much. To really get a feel for what car insurance costs, it helps to look at how these pricing factors play out in the real world. Let’s meet three different drivers in the Tampa Bay area. Each profile shows how a unique mix of age, car, location, and driving habits leads to a completely different annual premium.
This kind of storytelling makes the complicated world of insurance pricing much easier to grasp. By walking through these examples, you can start to see where your own profile fits in and why your quote is what it is.
Profile 1: The Young Student in Tampa
First up is Maya, a 21-year-old college student who rents an apartment near the University of South Florida. She drives a 2015 Honda Civic to get to class and her part-time job. She’s a pretty careful driver, but she did have a minor at-fault fender bender last year.
Maya’s insurance premium is on the high side, with a few key factors working against her:
- Age: As a driver under 25, she’s automatically placed in the highest-risk group from a statistical standpoint.
- Location: Her Tampa zip code is dense with traffic, which means a higher likelihood of accidents and theft compared to a sleepy suburb.
- Driving Record: That recent at-fault accident is a major red flag for insurers, immediately bumping up her risk profile.
Estimated Annual Premium: $5,200 – $6,500 for full coverage.
Maya’s rate is steep almost entirely because of her age and that recent accident. Insurers see that combination as a strong predictor of future claims, landing her in one of the most expensive pricing tiers.
Even though her older car is cheaper to fix, her personal factors are what’s really driving up the cost. To dig deeper into what makes Florida rates so high, check out our guide on why car insurance is so expensive in Florida.
Profile 2: The Suburban Family in Hillsborough County
Next, let’s look at the Garcia family, who live in a quiet suburban neighborhood in Hillsborough County. David is 45, Maria is 43, and they just added their 17-year-old son, Leo, to their policy. They own a 2023 Kia Telluride and a 2020 Toyota Camry, have spotless driving records, and bundle their auto and home insurance.
The Garcias have a more moderate risk profile, but one major cost driver is shaking things up.
- Teen Driver: Adding Leo, a brand-new driver, is one of the most expensive moves a family can make to their policy.
- New Vehicle: The 2023 SUV is expensive to repair or replace, which directly impacts the price of their collision and comprehensive coverage.
- Positive Factors: Their clean driving histories, bundling discount, and years of experience behind the wheel help to soften the blow.
Estimated Annual Premium: $6,800 – $8,200 for full coverage on both vehicles.
While David and Maria’s individual rates would be fairly reasonable, adding their teenage son causes the family premium to nearly double. This huge jump reflects the extremely high statistical risk that comes with inexperienced drivers.
Profile 3: The Retiree in a Quiet Community
Finally, meet Robert, a 68-year-old retiree living in a peaceful 55+ community. He drives his 2018 Buick LaCrosse less than 5,000 miles a year, mostly for errands and visiting his grandkids. He has a perfect driving record stretching back over 40 years and an excellent credit score.
Robert is basically the ideal low-risk customer for an insurance company.
- Excellent Driving History: Decades without an accident or a ticket make him a very safe bet.
- Low Mileage: Simply put, driving less means there’s less opportunity to get into an accident.
- Mature Driver: His age and experience are seen by insurers as signs of responsible driving habits.
Estimated Annual Premium: $2,400 – $3,100 for full coverage.
Robert’s profile is a perfect example of how consistently safe behavior and a low-risk lifestyle are rewarded with the best rates. He pays far less than the state average because just about every single pricing factor is working in his favor.
Practical Strategies to Lower Your Car Insurance Premiums
Knowing what goes into your car insurance bill is the first step, but the real power comes from taking action to lower it. The global car insurance market is massive—projected to hit USD 1.69 trillion by 2033—and it feels like rates are always climbing. But you’re not just along for the ride.
You can absolutely find ways to make your coverage more affordable without stripping away the protection you need. It just takes a little proactive effort.
Shop Around and Compare Quotes
If you do only one thing to save money, make it this: shop around. In the world of insurance, loyalty rarely gets you the best deal. The company that gave you a great rate a few years ago might not be your most competitive option now.
Every insurer has its own unique, and often secret, formula for assessing risk. That’s why you can get wildly different quotes for the exact same coverage. Make it a yearly habit to get quotes from at least three to five different companies, especially after a big life event like moving or buying a new car.
Ask About Every Available Discount
Insurance companies have a whole menu of discounts, but they won’t always serve them up automatically. You have to ask for them.
It’s smart to go down a checklist with your agent to see what you qualify for.
- Bundling Policies: This is an easy win. If you combine your auto insurance with your home or renters policy, you can often knock 10% to 25% off your premium.
- Safe Driver Discounts: Have you gone years without an accident or a ticket? That clean record is worth real money. Most insurers reward drivers who stay violation-free for three to five years.
- Good Student Discounts: If you have a full-time student on your policy with a “B” average or better, make sure your insurer knows. It can lead to a nice rate reduction.
- Safety Feature Discounts: Modern cars are packed with safety tech. Things like anti-lock brakes, airbags, and anti-theft systems can all trim a little more off your bill.
Don’t leave that money on the table. A quick call to your provider to review your policy for discounts could pay off instantly.
Adjust Your Deductible Strategically
Your deductible is what you agree to pay out-of-pocket on a claim before the insurance company steps in. By raising it, you’re telling the insurer you’re willing to share a bit more of the financial risk, and they’ll reward you with a lower premium.
How much can you save? Bumping your deductible from $500 up to $1,000 could lower your collision and comprehensive coverage costs by 15% to 30%.
Choosing a higher deductible is a calculated risk. It guarantees lower monthly payments, but you must have the cash on hand to cover it if you need to file a claim. It’s a great strategy if you have a healthy emergency fund.
By actively managing these parts of your policy, you can make a real dent in your insurance costs. If you’re still not sure if your rate is fair for our state, it’s worth exploring whether you are paying too much for Florida auto insurance. These tips put you back in the driver’s seat, helping you find that sweet spot between solid coverage and a price you can live with.
What Happens When Your Coverage Isn’t Enough?
https://www.youtube.com/embed/pZAT8jV3ny4
We all buy car insurance hoping we never have to use it. But what happens when you do, and the coverage—either yours or the other driver’s—just doesn’t cut it? After a crash, you find out fast what your policy is really worth, especially here in Florida where coverage gaps are a frustratingly common problem.
This becomes a nightmare scenario when you’re hit by a driver who is either uninsured or only carries the bare-minimum coverage required by law. Their tiny policy might put a small dent in your vehicle repair bills, but it will leave you holding the bag for massive medical expenses, lost time from work, and other long-term costs.
Your Financial Safety Net: Uninsured Motorist Coverage
This is exactly why Uninsured/Underinsured Motorist (UM/UIM) coverage is so incredibly important. Think of it as a backup plan you buy to protect yourself from other, less responsible drivers on the road. When the at-fault driver’s insurance is maxed out or doesn’t exist at all, your own UM/UIM policy kicks in to cover the difference.
It’s designed to pay for the exact same things the other driver’s insurance should have covered, including:
- Medical Expenses: Covers everything from the ambulance ride and ER visit to ongoing physical therapy and future surgeries.
- Lost Wages: If you can’t work because of your injuries, UM helps replace that lost income so you can keep your bills paid.
- Pain and Suffering: This also provides compensation for the physical pain and emotional trauma the accident has caused.
Without this protection, your only option is to hope the at-fault driver has enough personal assets to cover your losses. That’s a gamble you almost never win. To get a better handle on this, you can learn more about what uninsured motorist coverage is and why it’s a must-have for every Florida driver.
When Your Own Insurer Disputes a Claim
Unfortunately, having the right policy doesn’t always guarantee a smooth process. Insurance companies are for-profit businesses, and their primary goal is often to pay out as little as possible. It’s not unusual for an insurer to fight a perfectly valid claim, offer a ridiculously low settlement, or deny it outright.
An insurer might argue that your injuries aren’t as severe as you claim or that some of your medical treatments weren’t necessary. This tactic can leave accident victims feeling powerless and unsure of what to do next.
This is the moment when you need to stand up for your rights. If you’ve been in an accident in the Tampa area and feel your insurance company is playing games or acting in bad faith, you do not have to accept their first offer. Getting help from an experienced local attorney ensures your claim is taken seriously and that you fight for the full compensation you deserve. A lawyer can take over all communication with the insurer, gather the right evidence, and work to protect your financial future.
Frequently Asked Questions About Car Insurance Costs
Trying to make sense of Florida car insurance can leave you with more questions than answers. Let’s tackle some of the most common things drivers ask about what they’re paying and why.
Why Is Car Insurance So Expensive In Florida?
It’s not just your imagination; Florida’s rates really are high. This is because we have a perfect storm of factors that make insuring drivers here a risky business.
Think of it this way: our no-fault PIP system, a surprisingly high number of uninsured drivers, the constant threat of hurricanes, and rampant insurance fraud all get thrown into one big pot. For insurance companies, that recipe looks expensive, and they pass those costs down to all of us in the form of higher premiums.
How Much Does Insurance Increase After An Accident?
An at-fault accident will almost always make your rates go up, but there’s no magic number for how much. The final figure really depends on the specifics: how severe was the crash? Were you deemed at fault? What did your driving history look like before this?
A minor fender-bender might only cause a small bump in your premium. A serious collision, however, could trigger a significant rate hike that sticks with you for years.
The single best way to combat rising rates is to consistently shop around. Comparing quotes from multiple insurers annually can reveal significant savings, often amounting to hundreds or even thousands of dollars for the same level of coverage.
Can I Get Insured In Florida With A Bad Driving Record?
Absolutely. You can still find coverage in Florida, even if your driving record has a few blemishes, but be prepared for it to cost more.
Your best bet will be looking for insurance companies that specialize in what’s known as “high-risk” or non-standard policies. These insurers are set up to work with drivers who have past accidents or violations. The key to bringing those rates back down is to start building a clean driving record from today forward. Over time, that consistency proves you’re a lower risk.
If you’ve been hurt in a crash and the insurance company is giving you the runaround with an unfair settlement offer, you don’t have to take them on by yourself. The team at Martin Hernandez, P.A. fights for the rights of accident victims across Tampa. We’re here to help you demand the full compensation you’re entitled to. Get in touch for a free consultation at https://injurylawyersoftampa.com.