
So, your car is back from the body shop after a wreck in Tampa. It looks great, drives like a dream, and you’re just happy to have it back. But there’s an invisible problem that even the best mechanic can’t fix: its new accident history.
That history, now permanently stamped on vehicle reports like CARFAX, can quietly strip thousands of dollars from your car’s resale value. This loss is called diminished value, and a diminished value claim is your tool for getting that money back.
The Stigma of an Accident History
Think about it from a buyer’s perspective. You’re looking at two identical used cars. Same make, same model, same mileage. One has a clean history, and the other was in a collision but expertly repaired. Which one would you pay more for?
Exactly. The same logic applies to your vehicle. Even with flawless, factory-certified repairs, the simple fact that it was in an accident makes it less desirable on the open market. This is the stigma that causes the drop in value.
A diminished value claim isn’t about paying for the repairs you just had done. It’s about recovering the market value that vanishes after those repairs are complete, simply because the car now has an accident on its record.
Navigating Your Rights in Florida
The good news is that in Florida, you have a legal right to go after this loss from the at-fault driver’s insurance company.
But filing a claim isn’t as simple as just telling the insurer your car is worth less. You have to prove it. Beyond just getting the car fixed, it’s critical to know how to protect yourself legally and medically after a car accident.
This guide will walk you through the entire process, showing you how to build a strong case and fight for the compensation you’re owed. For a refresher on what to do immediately following a collision, take a look at our complete guide on what to do after a car accident in Florida.
Breaking Down the Types of Diminished Value
When we talk about diminished value, it’s not a one-size-fits-all concept. The loss your car suffers after a wreck in Florida typically breaks down into two main types. Getting a handle on which one applies to your car is the first, and most important, step in building a solid claim.
The most common kind, and the one that affects nearly every repaired vehicle, is called inherent diminished value. This is the immediate, automatic drop in your car’s resale value simply because it now has an accident history. It doesn’t matter if the best body shop in Tampa made the car look brand new; that accident is now part of its permanent record, and a smart buyer will never pay top dollar for it.
Inherent Diminished Value: The “Accident Stigma”
Let me put it another way. Imagine you’re looking to buy a used SUV. You find two identical models, same year, same mileage. One has a clean vehicle history report, but the other shows it was in a moderate collision a year ago. Even if it looks perfect, you’re going to offer less for the one that was wrecked, right?
That price difference is exactly what inherent diminished value is. It’s not some imaginary number; it’s a real financial loss you’ll face the day you try to sell or trade in that vehicle. And since the at-fault driver caused that loss, you deserve to be compensated for it.
Repair-Related Diminished Value: When the Repairs Aren’t Right
Then there’s the second category: repair-related diminished value. This is the extra loss in value that happens when the body shop just doesn’t get the job done right. It’s a separate loss that gets piled on top of the inherent diminished value we just talked about.
You’ve probably seen this before. It shows up as:
- Mismatched Paint: The new paint job has a slightly different shade or sheen than the original factory paint.
- Poor Panel Gaps: The spaces between the doors, hood, or trunk are noticeably uneven.
- Aftermarket Parts: The shop used cheaper, non-original parts, which can compromise the car’s quality and value.
- Lingering Mechanical Problems: Maybe the car now pulls to one side or you hear a new noise that wasn’t there before the crash.
When these kinds of flaws are left behind, your car is worth even less than it would be just from the accident stigma alone.
It’s crucial to understand that a car can suffer from both types of diminished value at the same time. The accident creates an inherent loss, and shoddy repairs can make that financial hit even worse.
In reality, experts often identify three forms—inherent, repair-related, and the immediate pre-repair loss—which can easily slash 10-25% from a car’s pre-accident value. For a $30,000 vehicle, that’s a $3,000 to $7,500 loss you’re left with. This is a huge deal, especially for Tampa rideshare drivers who often see insurers try to wiggle out of paying these claims. To dig deeper into how these value types are professionally evaluated, The Auto Mediator offers a really comprehensive guide.
How Insurance Companies Undervalue Your Claim
When you file a diminished value claim, you’re stepping into an arena with a business that has perfected the art of minimizing payouts. Insurance companies are not in the business of paying you what your car has truly lost in value; their primary goal is to protect their bottom line. They have a well-worn playbook for undervaluing your claim, and you can bet their first offer is just a lowball tactic.
They want you to believe their calculation is the final word. But their initial number is almost always just a starting point, cooked up using internal formulas that are designed to save them money, not to make you whole again.
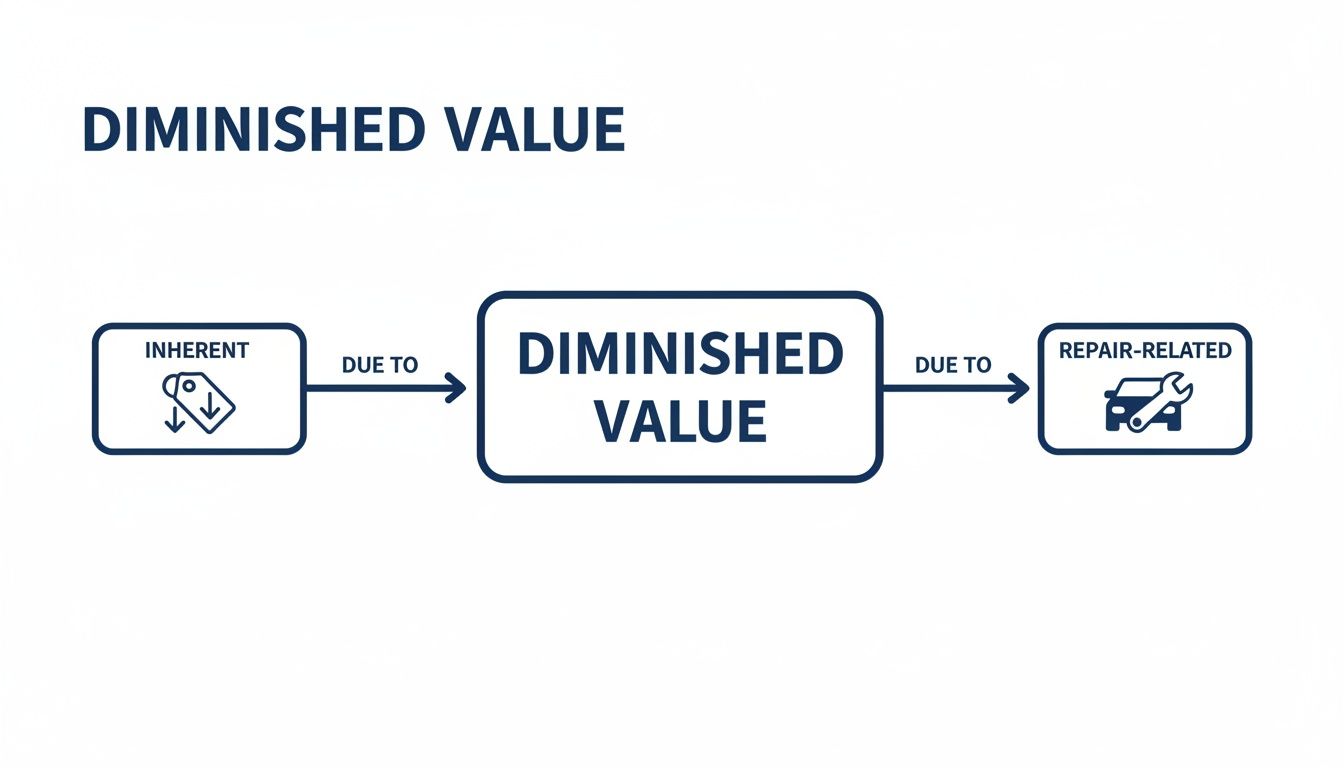
As you can see, your car’s value drops either from the simple fact it’s been in a wreck (inherent) or because the repairs weren’t perfect (repair-related). Insurance adjusters will do their best to downplay both.
Unmasking the 17c Formula
One of the most notorious tricks up an adjuster’s sleeve is the “17c formula.” Don’t be fooled by the official-sounding name—this isn’t a law in Florida. It’s a calculation cooked up by the insurance industry for the sole purpose of producing the lowest possible diminished value number.
The formula kicks off by capping the maximum possible loss at a mere 10% of your car’s pre-accident value. From that already low ceiling, they start hacking away with more deductions.
- Damage Modifier: This is where an adjuster gets creative. They might classify serious frame damage as “moderate” just to shrink the payout.
- Mileage Modifier: They’ll also hit you with a big reduction for higher mileage, arguing your car was already worth less to begin with.
It’s crucial to understand that the 17c formula has no legal weight in Florida. It is simply the insurance company’s self-serving math. You are under no obligation to accept a settlement based on it.
What you’re left with is an offer that might only be a tiny fraction of what your car actually lost in market value. This isn’t an accident; it’s a strategy. Knowing this is your first step in fighting for what you’re owed. This is just one of many reasons why insurance companies deny claims or make insulting offers. When you understand their playbook, you can challenge their numbers with your own independent evidence.
Navigating Florida Laws for Diminished Value Claims
One of the biggest hurdles for drivers in Florida is just understanding the rules of the road when it comes to insurance. Many people hear “no-fault state” and assume they’re out of luck, but that’s a common and costly mistake.
Florida’s no-fault system only applies to your own personal injuries. When it comes to the damage to your car—and that includes its lost resale value—the law is on your side. You have the right to file a third-party claim directly against the at-fault driver’s insurance company to get back what you’ve lost.
The Right to File a Third-Party Claim
Let’s clear up a major myth: you are not stuck dealing only with your own insurance company. Far from it. In Florida, you are allowed to go directly after the insurer of the person who caused the wreck. This is your most direct path to recovering diminished value. For an overview of how this differs from other places, you can explore valuable insights on TeamJustice.com.
For Tampa drivers, this is a critical right. Settlements often land in the range of 10-25% of a vehicle’s pre-accident value. A car worth $20,000 before the crash could bring a diminished value recovery of $2,000 to $5,000, and that number climbs significantly for high-end vehicles or cars with major structural damage.
Florida’s Statute of Limitations
Time is not on your side after an accident. Florida law sets a strict deadline, known as the statute of limitations, for taking legal action to recover property damage. If you miss this window, you lose your right to sue forever.
In Florida, you generally have four years from the date of the crash to file a lawsuit for property damage, which includes your diminished value claim. Waiting too long means the courthouse doors are permanently closed to you.
That’s why it’s so important to get the ball rolling quickly. Building a strong claim takes time—you have to gather repair records, get appraisals, and negotiate with the insurance company. Don’t let the clock run out on you. For a deeper dive into these deadlines, you can learn more about the Florida statute of limitations for car accidents.
Complex Cases Involving Commercial Vehicles
Things get a lot more complicated if you were hit by a commercial vehicle like a delivery van, a semi-truck, or a rideshare car. These aren’t simple fender-benders; they often involve powerful corporations and multiple layers of insurance coverage.
Imagine a collision with a large commercial truck. You could be dealing with:
- The truck driver’s individual insurance.
- The trucking company’s massive commercial liability policy.
- A separate insurance policy for the trailer owner.
Figuring out who to sue and untangling the web of corporate policies is a nightmare for most people. This is exactly where an experienced Tampa attorney can make all the difference, making sure your claim is filed correctly against every single responsible party.
Your Step-by-Step Guide to Filing a Successful Claim
Knowing you’re entitled to a diminished value claim is one thing, but actually getting the insurance company to pay up is a whole different ball game. So, let’s walk through the practical steps you can take as a Tampa resident to turn that knowledge into a check in your hand. The secret is building a case so solid that the insurer simply can’t ignore it.
It all begins with documentation—and I mean meticulous documentation. From the moment the accident happens and all the way through the repair process, you need to be in evidence-gathering mode.
Gathering Your Core Evidence
Your claim is only as strong as the proof you have to back it up. Before you even think about calling the insurance adjuster about diminished value, get these documents in order:
- The Official Police Report: This is your foundation. It lays out the basic facts of the crash and, most importantly, who was ticketed for causing it.
- Detailed Photographs: You need a “before and after” story in pictures. Get clear photos showing all the damage before any repairs start, and then take photos of the finished work to document its quality.
- Itemized Repair Bills: The final invoice from the auto body shop is a critical piece of evidence. It details every single part that was replaced and every hour of labor that went into fixing your car.
Once you have your evidence organized, it’s time to make your most important move.
The single best thing you can do for your claim is to hire an independent, certified appraiser. Their professional, unbiased report calculating your car’s exact loss in value is your number one weapon against the insurance company’s inevitable lowball offer.
Building and Submitting Your Claim
With that independent appraisal in hand, you’re officially ready to demand what you’re owed. The first formal step in making your what is diminished value claim is typically sending a powerful demand letter to the at-fault driver’s insurance company. This letter needs to state the specific dollar amount you’re claiming, with your appraisal and other evidence attached to support it.
Keep in mind there are deadlines for filing. If you’re unsure about the timing, our guide explains how long you have to report an accident to insurance.
Historically, a key legal case established that insurers must pay for diminished value even when a car was perfectly repaired. This precedent still influences how claims are handled in big markets like Florida. It also led to the creation of formulas like “17c”—which, while usually producing lowball offers, prove that diminished value is a very real, legally recognized loss.
Your independent appraisal is the key to proving your actual loss and countering the insurer’s attempt to pay you less than you deserve.
Why You Need a Tampa Attorney for Your Claim
Sure, you can try to file a diminished value claim on your own. But it’s a lot like stepping into a professional negotiation with no experience. Insurance companies aren’t on your side; they have entire teams dedicated to protecting their bottom line. That means paying out as little as possible on claims just like yours.
Hiring a seasoned Tampa attorney changes the dynamic instantly. We level the playing field.
From the moment we take your case, we become your shield and your advocate. All communication from the insurance company has to go through us. This puts an immediate stop to adjusters pressuring you, twisting your words, or trying to rush you into a tiny, lowball settlement before you know what your claim is really worth.
Maximizing Your Recovery with Expertise
A good lawyer does far more than just fill out forms. We know exactly who the credible, certified auto appraisers are right here in the Tampa area—the ones whose reports will stand up to scrutiny from the insurance company’s own experts.
This detailed appraisal becomes the cornerstone of our strategy. We build a powerful, evidence-based argument that makes it incredibly difficult for the insurer to simply dismiss your car’s lost value.
Our deep knowledge of Florida insurance laws and how Hillsborough County courts operate gives us a home-field advantage. We’ve seen the insurance companies’ playbooks countless times, and we know how to counter their common tactics to get you the maximum payout you deserve.
A personal injury attorney transforms your claim from a simple request into a credible legal demand. We force the insurance company to take your loss seriously and negotiate in good faith.
No Upfront Costs, No Financial Risk
We understand that after an accident, the last thing you need is another bill. That’s why our firm handles these cases on a contingency fee basis.
It’s simple: you pay us absolutely nothing unless and until we win your case and recover money for you. There are no retainers or upfront fees to worry about. This approach makes expert legal help accessible to everyone, regardless of their financial situation.
This arrangement means we’re in this together. Our goals are perfectly aligned with yours, removing any financial risk from your shoulders so you can focus on moving forward. If you’re wondering what to look for in legal help, check out our guide on how to find a good injury lawyer.
Common Questions We Hear About Diminished Value
Even with a grasp of the basics, it’s natural to have more questions about how a diminished value claim actually works in the real world. Here are some straightforward answers to the questions we get asked most often by drivers here in Tampa.
Can I File a Diminished Value Claim Against My Own Insurance Policy in Florida?
This is a big point of confusion, and the answer in Florida is a firm no. You can’t claim diminished value under your own policy.
Think of it this way: a diminished value claim is a third-party claim. You’re seeking compensation from the at-fault driver’s insurance company for the loss they caused to your car’s market value. Your own collision coverage is there to pay for the repairs themselves, not to make up for the stigma of an accident history.
What’s a Realistic Expectation for My Claim’s Worth?
There’s no magic formula, because every car and every accident is different. But as a general starting point, a claim often falls somewhere between 10% and 25% of your vehicle’s pre-accident value, according to sources like Kelley Blue Book or NADA.
Of course, several factors will push that number up or down:
- The Car Itself: A high-end luxury car, a classic, or a rare model will almost always lose a bigger chunk of its value than a standard sedan.
- Age and Mileage: Newer cars with fewer miles on the odometer take the biggest hit. The value drop is less dramatic for older, high-mileage vehicles.
- The Damage Done: If the accident caused structural or frame damage, the diminished value will be significant. Minor cosmetic dings and scratches? Much less so.
This is exactly why getting an independent appraisal is so critical. It’s the only objective way to pin down the true financial loss for your specific situation.
What if the At-Fault Driver’s Insurance Company Is Ignoring Me?
First off, don’t panic. This is a common tactic. If an adjuster is giving you the silent treatment after you’ve sent your demand letter or is simply refusing to negotiate, they may be operating in bad faith under Florida law. You don’t have to just accept it.
An insurance company’s silence isn’t a “no.” It’s often a strategy to see if you’ll give up and go away. It’s a sign that you need to ramp up the pressure.
This is where having an attorney in your corner really changes the game. We can step in and send a formal legal demand that they can’t ignore. We’ll follow up persistently, and if they still won’t cooperate, we can file a lawsuit to force their hand. That legal leverage is often the key that unlocks a fair negotiation and gets you the compensation you deserve.
If you’re getting the runaround from an insurance company over your diminished value claim, you don’t have to fight them by yourself. The team at Martin Hernandez, P.A. knows their playbook and has the experience to fight for the full value you’ve lost. Reach out to us for a free, no-pressure consultation to discuss your rights and see how we can help at https://injurylawyersoftampa.com.