
When you’re found legally responsible for causing an accident, liability insurance is your financial backstop. Put simply, it’s the part of your policy that pays for the other party’s injuries and property damage—not your own—protecting your personal assets from being wiped out by a lawsuit. This coverage is the bedrock of responsible driving here in Florida.
Your Financial Shield After a Car Accident
Picture this: you cause a multi-car pileup on the Howard Frankland Bridge during rush hour. The aftermath is a chaotic scene of crumpled vehicles, serious injuries, and rapidly mounting expenses. If you didn’t have the right insurance, the financial weight of every medical bill and car repair would land squarely on your shoulders.
This is exactly the scenario where liability insurance becomes your most critical asset. Think of it as a protective wall between your personal savings, your home, and your future earnings and the staggering costs of an accident you caused. It’s specifically designed to handle the claims made against you, so a single mistake behind the wheel doesn’t spiral into complete financial ruin.
The Two Core Components of Liability Coverage
Liability insurance isn’t just one big pot of money; it’s split into two distinct parts that work in tandem to protect you. Getting a handle on these components is key to understanding what your policy actually does after a crash.
- Bodily Injury (BI) Liability: This is the part that covers medical bills, lost wages, and pain and suffering for the people you injure in an accident.
- Property Damage (PD) Liability: This coverage pays to repair or replace the other person’s property. Most often it’s their car, but it could also cover a damaged fence, a mailbox, or other structures.
One part handles the human cost, the other handles the physical damage. You absolutely need both for real protection.
In Florida, the consequences of driving without enough liability coverage can be devastating. If you cause an accident with injuries, you could be sued personally, putting everything you’ve worked for on the line.
Why This Coverage Is Essential in Florida
While Florida has specific insurance laws, just carrying the state minimum often isn’t nearly enough to protect your financial future. A serious accident can easily rack up costs that blow past minimum policy limits, leaving you personally exposed for the rest.
For example, if you cause a wreck that sends the other driver to the hospital for surgery, their medical bills could easily top $50,000. If your Bodily Injury liability limit is only $25,000, you are personally on the hook for the remaining amount. This is why it’s so critical to understand your policy’s limits.
Many drivers ask, does full coverage include liability insurance in Florida? The answer is a definite yes. In fact, liability is the foundation of any solid auto insurance policy, setting the stage for how all your other coverages work together to keep you secure.
Bodily Injury vs. Property Damage: What’s the Difference?
When you hear the term “liability insurance,” think of it as your financial shield. It’s the part of your auto policy designed to protect your assets if you’re found responsible for a crash. At its heart, liability coverage is split into two distinct, but equally important, categories: Bodily Injury and Property Damage.
Understanding how each one works is the key to grasping what your insurance actually does for you in a real-world accident. These coverages are your first line of defense, stepping in to pay for the other party’s losses so you don’t have to drain your bank account or sell your home.
Bodily Injury Liability: Covering the Human Cost
Bodily Injury (BI) liability is arguably the most critical coverage you can have. It’s designed to cover the human side of an accident you cause—the medical bills, lost income, and the pain and suffering of anyone you injure. The costs associated with serious injuries can be staggering, and BI liability is what stands between you and financial ruin.
Let’s paint a picture. You’re driving down I-275 in Tampa, and for just a split second, you glance at your GPS. In that moment, traffic comes to a screeching halt. You slam on the brakes, but it’s too late. The driver in the car you rear-ended suffers a serious back injury that requires surgery and months of missed work.
This is where your BI coverage kicks in. It would be used to pay for:
- The ambulance, hospital bills, and surgical procedures.
- The income they lose while they are out of work recovering.
- Compensation for their physical pain and the emotional trauma of the crash.
Without it, you’d be on the hook for those expenses personally. A lawsuit could target your savings, your home, and even your future earnings.
Bodily Injury liability is your defense against a lawsuit that could wipe you out financially. It’s built to handle the most unpredictable and potentially devastating cost of a car crash: the physical harm done to another person.
Property Damage Liability: Fixing What Was Broken
While BI liability covers people, Property Damage (PD) liability covers, well, their stuff. Most of the time, this means paying to repair or replace the other person’s vehicle. But it doesn’t stop there.
Imagine you swerve to miss a dog and end up driving through someone’s fence and into their prized rose garden. Your PD liability is what pays to fix the fence and restore the landscaping. In Florida, carrying PD coverage is mandatory, for good reason—it ensures that drivers can pay for the physical destruction they cause. This can range from major structural repairs to addressing common car damages like scratches that you caused.
Understanding Your Policy Limits
Every liability policy has its limits—the absolute maximum your insurance company will pay out for a single claim. Anything beyond these limits is your personal responsibility. You’ll typically see these limits written as a series of three numbers, like 100/300/50.
Here’s a simple breakdown of what that means:
- $100,000: The maximum payout for Bodily Injury for any one person you injure.
- $300,000: The maximum total payout for Bodily Injury for the entire accident, no matter how many people are hurt.
- $50,000: The maximum payout for all Property Damage in a single accident.
Learning to read these numbers is crucial for knowing just how protected you are. And while BI and PD are the foundation, it’s wise to ask yourself if liability is the only auto insurance coverage you need, because other types of coverage exist to fill some very important gaps.
How Florida’s No-Fault Law Actually Works
Florida’s “no-fault” car insurance system is probably one of the most misunderstood topics for drivers. When people hear “no-fault,” they often think it means no one is ever held responsible for causing a crash. That couldn’t be further from the truth.
Fault is absolutely essential in determining who pays for serious damages. The no-fault part of the law just changes how the initial bills are handled right after an accident.
To drive legally in Florida, you’re required to have $10,000 in Personal Injury Protection, or PIP, coverage. This is the heart of the no-fault system.
Your Personal First-Aid Kit
The easiest way to think about your PIP coverage is as your own personal financial first-aid kit. It’s the policy you turn to first, regardless of who was at fault for the accident.
The whole point is to get you immediate access to money for medical care and lost wages without getting bogged down in a long investigation. It’s completely different from liability insurance, which is designed to pay for the other person’s damages when you cause a wreck.
Your PIP benefits are set up to cover:
- 80% of your necessary and reasonable medical bills.
- 60% of your documented lost wages if the crash leaves you unable to work.
This setup ensures you can see a doctor right away. But that $10,000 limit gets used up incredibly fast, even in a relatively minor collision. This is where fault suddenly becomes the most important factor in your case. For a more detailed breakdown, you can review this Florida no-fault insurance explanation.
When Fault Takes Over: The Serious Injury Threshold
So what happens when that $10,000 in PIP is gone and you’re still facing a mountain of medical bills? This is where you can step outside the no-fault system by meeting Florida’s “serious injury threshold.”
Once your injuries are severe enough to meet this legal standard, you can finally pursue a claim against the driver who was actually at fault. Their Bodily Injury (BI) liability insurance is then supposed to kick in and cover everything your PIP didn’t.
In Florida, a “serious injury” is defined as one that results in significant and permanent loss of an important bodily function, permanent injury within a reasonable degree of medical probability, significant and permanent scarring or disfigurement, or death.
When you cross this threshold, you can demand that the at-fault driver’s insurance pay for all your remaining medical expenses, your full lost income, and your non-economic damages like pain and suffering—something PIP never covers.
This flowchart gives a simple visual of how liability insurance comes into play when you are at fault.
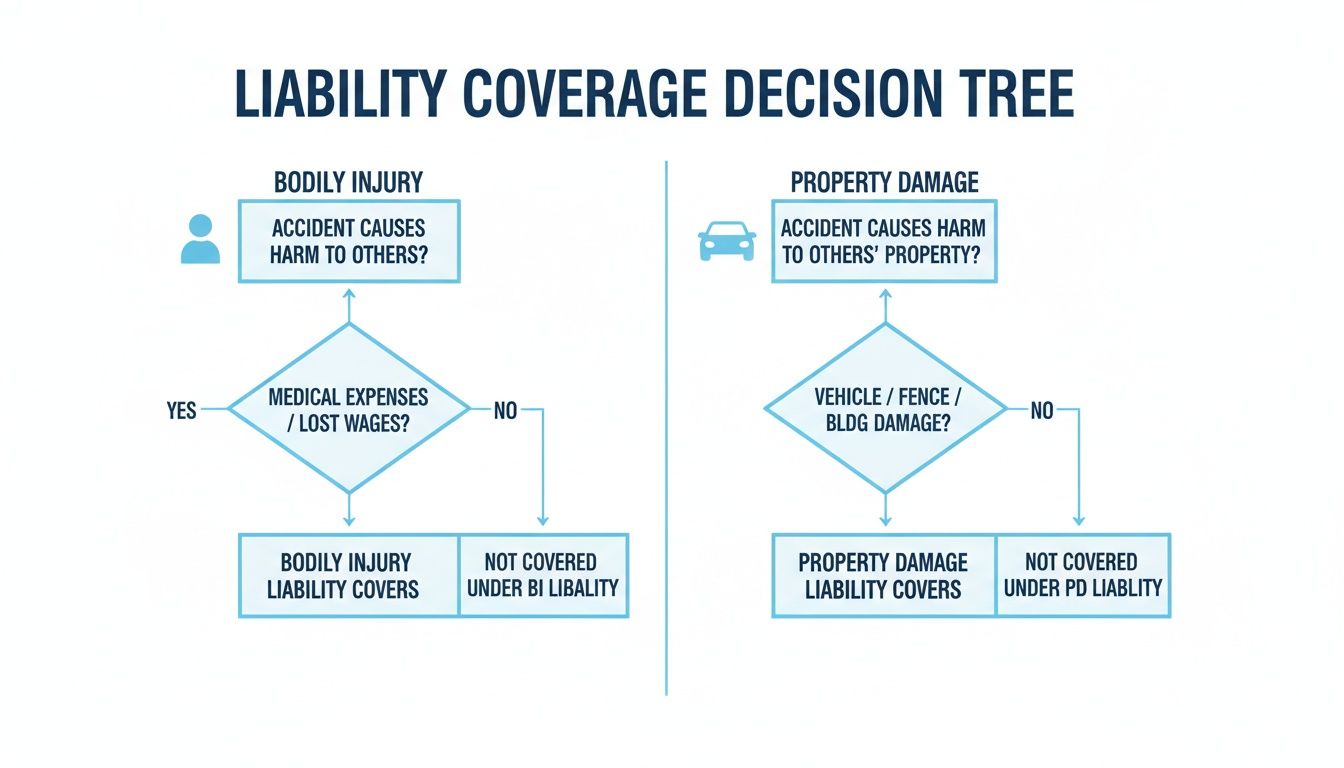
As you can see, the decision splits into two paths: Bodily Injury for hurting people and Property Damage for wrecking things.
The real danger here is that BI liability coverage isn’t required for most drivers in Florida. If you cause a serious crash and only carry the state minimum PIP and Property Damage (PD) coverage, your personal assets are completely exposed. Your PIP takes care of your own initial bills, but you’d have zero coverage for the other person’s major injuries, leaving you on the hook to pay for them yourself.
Protecting Yourself From Uninsured Drivers
Up to this point, we’ve been talking about how your liability insurance protects your assets if you cause a crash. But let’s flip the script. What happens if someone hits you, causing serious injuries, and they have little or no insurance to cover your losses?
This isn’t some far-fetched scenario; it’s an unfortunate reality on Florida’s roads. Our state has one of the highest rates of uninsured drivers in the country, which means your risk of getting hit by someone who can’t pay for the damage they cause is dangerously high.
When the at-fault driver’s insurance is worthless or non-existent, your own Bodily Injury (BI) liability coverage won’t help you one bit. Remember, it’s designed to pay other people, not you. This is exactly why another type of coverage is so essential.
Your Financial Safety Net: Uninsured Motorist Coverage
This is where Uninsured/Underinsured Motorist (UM/UIM) coverage steps in to become your financial safety net. The easiest way to think about it is as a stand-in for the at-fault driver’s missing insurance policy. It’s there to pay for your damages when the other driver can’t.
You’re essentially buying an insurance policy for yourself to use when you’re the victim of someone else’s mistake. This crucial coverage can pay for:
- Medical bills that go beyond what your PIP coverage handles.
- Lost wages if you’re out of work recovering from your injuries.
- The very real costs of your pain, suffering, and emotional trauma.
Without UM coverage, your only real option is to sue the at-fault driver personally. If they have no money or assets—which is often the case—that lawsuit won’t get you very far. You can learn more in our detailed guide on what uninsured motorist coverage is.
Uninsured Motorist coverage isn’t just a policy add-on; it’s a vital shield that protects you and your family from the irresponsible choices of other drivers.
A Tale of Two Cyclists: The Power of UM Coverage
To see just how powerful UM coverage can be, let’s look at the stories of two cyclists, Alex and Maria. Both were hit by uninsured drivers in separate crashes.
Alex had only the bare-minimum PIP and property damage coverage. After a driver blew through a red light and hit him, his medical bills blew past his $10,000 PIP limit in no time. With no UM coverage to fall back on, he was drowning in medical debt and had no way to recoup his lost wages. The at-fault driver had no assets, leaving Alex financially shattered by an accident he didn’t cause.
Now, consider Maria. She had a solid auto policy that included $100,000 in UM coverage. When she was the victim of a hit-and-run, her own insurance company stepped up. Her UM policy covered all her excess medical bills, paid back the months of income she lost while recovering, and compensated her for her significant pain and suffering. She was able to focus on getting better, not on the verge of financial ruin.
These two outcomes couldn’t be more different, and they perfectly illustrate why UM coverage is non-negotiable in Florida. The financial risk is only growing, with the global liability insurance market projected to jump over 90% to $524.66 billion by 2034, fueled by massive jury awards and litigation risks. Carrying enough UM coverage is one of the smartest things you can do to protect yourself.
What to Do After a Car Wreck in Florida
In the moments after a car crash, it’s easy to feel overwhelmed. Your head is spinning, adrenaline is pumping, and it’s hard to think clearly. But what you do right then and there can make a huge difference, both for your health and for your ability to get fair compensation later on.
Protecting your rights from the very beginning is the key to navigating the confusing insurance claims process. Every step, from getting medical help to documenting the scene, helps build the foundation for a solid claim.
Your First Moves at the Crash Scene
The absolute first priority is safety. If it’s possible, move your car out of the flow of traffic. Check on yourself and your passengers, then, if you’re able, check on the people in the other vehicle.
Once everyone is as safe as possible, it’s time to shift into information-gathering mode. This evidence is what you’ll rely on to prove who was at fault and what really happened.
- Dial 911 Right Away: A police report is an official, unbiased account that insurance adjusters take seriously. It locks in the basic facts: the date, time, location, and the officer’s initial take on the situation. Don’t skip this, even for a “minor” fender bender.
- Become a Documentarian: Pull out your phone. Take photos and videos of everything—the damage to both cars, the positions they’re in, the surrounding intersection, traffic signs, and any injuries you can see. Make sure you get the other driver’s contact and insurance details.
- See a Doctor: Adrenaline is a powerful painkiller. It can easily hide serious problems like whiplash, a concussion, or even internal injuries. Getting checked out by a doctor right away creates a medical record that officially links your injuries to the accident.
We’ve put together a more detailed checklist in our guide on what to do after an accident that walks you through everything.
Why You Need a Legal Advocate on Your Side
Once the dust settles, you’ll have to deal with insurance companies. Here’s a critical fact to remember: the other driver’s insurance adjuster is not your friend. Their job is to protect their company’s profits, which means paying you as little as possible—or nothing at all. This is where a personal injury lawyer becomes your most valuable ally.
Think of a skilled attorney as your shield. They step in and handle every phone call, email, and letter from the insurance company, preventing adjusters from twisting your words. They manage the deadlines and the mountains of paperwork so you can focus on getting better.
An experienced law firm does more than just file papers. We dig deep to prove fault, often working with accident reconstruction experts, tracking down witnesses, and piecing together the evidence to build a case the insurer can’t just brush aside.
Calculating and Fighting for What You’re Owed
A lawyer’s job also involves figuring out the true value of your claim, which goes far beyond the first stack of medical bills. We calculate the cost of future treatments, lost income from missing work, any impact on your ability to earn a living down the road, and the very real cost of your pain and suffering.
Insurers are pushing back harder than ever. With casualty and liability insurance rates in the US jumping 8% recently, driven by massive jury awards, their motivation to deny and devalue claims is at an all-time high. Having a professional who knows their playbook is the only way to level the playing field.
Finally, never underestimate the mental and emotional toll of a crash. Getting help is a sign of strength. Resources like a guide to ICBC counselling after an accident can be an incredible support system for your mental recovery during this tough time.
Common Questions About Florida Liability Insurance
Trying to make sense of auto insurance can feel like deciphering a foreign language. You hear terms like “liability,” “no-fault,” and “PIP” all the time, but they often create more questions than answers. Let’s clear up the confusion and tackle some of the most common questions Florida drivers have about what their insurance coverage really means.
What Are the Minimum Insurance Requirements in Florida?
To legally put a license plate on your car in the Sunshine State, you only need two kinds of coverage. The state-mandated minimum is shockingly low, and frankly, it leaves most drivers dangerously underinsured.
Here’s the bare minimum you’re required to have:
- $10,000 in Personal Injury Protection (PIP): This is the foundation of Florida’s no-fault system. It covers 80% of your initial medical bills and 60% of lost wages, no matter who was at fault for the crash.
- $10,000 in Property Damage Liability (PDL): This coverage pays for the damage you cause to someone else’s car or property, like a mailbox or fence.
See what’s missing? Bodily Injury (BI) liability—the coverage that pays for the injuries you cause to other people—is not required for most drivers. This creates a huge gap. If you cause a crash that injures someone, the state’s Financial Responsibility Law will then force you to buy BI coverage. But by then, the damage is done, and you’re already personally on the hook for the injuries from that first accident.
If Florida Is a No-Fault State, Why Do I Need Bodily Injury Liability?
This is easily one of the most misunderstood parts of Florida’s insurance laws. The “no-fault” concept only applies to your own initial, relatively minor medical bills paid by your PIP policy. It’s a system designed to get you quick access to medical care without getting bogged down in a lengthy investigation to determine who was at fault.
But the no-fault system has a clear stopping point. If an injury is severe enough to cross Florida’s “serious injury threshold”—think permanent injury, significant scarring, or disfigurement—the injured person can step outside the no-fault system. Once that happens, they have every legal right to sue you directly for all of their damages.
This is exactly why Bodily Injury liability is so critical. It’s the coverage that protects your personal assets when someone sues you for things PIP never touches, like pain and suffering. Without BI, you’d have to pay those damages out of your own pocket, putting your home, savings, and future earnings at risk.
How Much Liability Coverage Should I Actually Carry?
While the state minimums will keep you legal, they provide almost no real-world protection in a serious crash. A single trip to the emergency room can burn through your entire $10,000 PIP limit, and it doesn’t take much to cause more than $10,000 in damage to a modern car. Relying on minimum coverage is a massive financial gamble.
Most legal and financial experts agree that you should carry much higher limits to truly protect yourself. A smart starting point for most people is:
- $100,000 per person for Bodily Injury liability
- $300,000 per accident for Bodily Injury liability
- $100,000 for Property Damage liability
On an insurance policy, this is often written as 100/300/100. If you own a home or have significant savings, you should seriously consider even higher limits or adding an umbrella policy for extra protection. It’s also wise to match your Uninsured Motorist (UM) limits to your BI limits, giving yourself the same level of protection you’re extending to others.
Does Liability Insurance Cover Me if I Drive a Friend’s Car?
This question pops up all the time. The answer usually comes down to a simple principle: in most cases, auto insurance follows the vehicle, not the driver.
So, if you get permission to drive a friend’s car and you cause an accident, their auto insurance is on the hook first. It’s considered the primary coverage. This means their insurance company is responsible for paying for the damages up to the limits of their policy.
Your own liability insurance would then step in as secondary coverage. It would only be used if the accident causes more damage than your friend’s policy can cover. For instance, if you cause $40,000 in property damage but your friend only carries a $25,000 PDL limit, your policy could potentially kick in to cover the remaining $15,000. It’s always a good idea to make sure a friend’s insurance is active before you get behind their wheel.
Getting a handle on the details of liability insurance is your best defense against financial disaster after a crash. If you’ve been injured and are stuck fighting an insurance company for fair compensation, you don’t have to go it alone. The experienced team at Martin Hernandez, P.A. is here to protect your rights and fight for the full amount you deserve. Contact us today for a free, no-obligation consultation to discuss your case.